“Bedford” on a market report can mean the Town of Bedford, a brokerage’s wider Bedford-area boundary, or a narrower postal or hamlet cut. Bedford Village, Bedford Hills, Katonah, and Bedford Corners trade in different competitive sets. Multi-acre estate parcels with outbuildings, private wells and septic do not compete with in-hamlet Colonials on smaller lots, and the few condo and co-op sales are a separate product altogether. A Bedford median is a useful temperature check. It is not a value opinion for any one house. An appraisal still has to match the subject’s location within Bedford, product type, condition, lot size and utility, and the effective date.
This October 2026 Insights post reads the latest closed-sale statistics the way an appraiser does: price level, inventory, days on market (DOM), sale-to-list, and closed volume, with no lifestyle framing. It complements the methodology piece Appraising Homes in Bedford, NY and does not replace a property-specific assignment. Local residential coverage is described on the firm’s Bedford appraisal page.
Sources: Three public series are used below. The primary is the Houlihan Lawrence Bedford Single Family Monthly Market Report for September 2026 (OneKey MLS). The second is the William Pitt Sotheby’s Bedford Market Tracker for September 2026. The third is the Homix OneKey-based Bedford report (data as of October 8, 2026), which reports only seven September closings against thirty-plus in the other two and is clearly a much narrower geographic filter. Different filters produce different counts. That is expected. Appraisers reconcile competing series by reading the filter first, then the number, and by verifying current MLS closed sales for the assignment’s effective date.
September 2026: Bedford Single-Family Snapshot
Houlihan Lawrence’s Bedford single-family table for September 2026 shows:
- Median sale price: $1,500,000 (+25.0% versus August 2026; +23.9% versus September 2025)
- Average sale price: $2,161,708 (+33.7% MoM; +61.1% YoY)
- Units sold: 33 (+26.9% MoM; +73.7% YoY)
- Average DOM: 40 days (+37.9% MoM; −11.1% YoY)
- Sale-to-list (% of sales price): 101.03% (+0.8% MoM; +2.1% YoY)
- Units for sale: 50 (+2.0% MoM; +4.2% YoY)
- Months of inventory: 1.50 (−21.1% MoM; −40.0% YoY)
Year-to-date context from the same report’s ten-year table (through September 30, 2026): the YTD median sold price is listed as $1,434,500, about 6% above the 2025 full-year median of $1,350,000 on that table. For scale, the same table shows full-year medians of $750,000 in 2017 and $1,195,000 in 2024, so the 2026 YTD median is roughly 91% above the 2017 figure.
| Metric (Bedford SF, HL / OneKey) | Sep 2026 | vs Aug 2026 | vs Sep 2025 |
|---|---|---|---|
| Median sale price | $1,500,000 | +25.0% | +23.9% |
| Average sale price | $2,161,708 | +33.7% | +61.1% |
| Units sold | 33 | +26.9% | +73.7% |
| Average DOM | 40 days | +37.9% | −11.1% |
| Sale-to-list | 101.03% | +0.8% | +2.1% |
| Units for sale | 50 | +2.0% | +4.2% |
| Months of inventory | 1.50 | −21.1% | −40.0% |
Source: Houlihan Lawrence Bedford Single Family Monthly Market Report, September 2026 (OneKey MLS). Figures deemed reliable but not guaranteed; not a value opinion for any subject property.
In Bedford, September was a high-volume, tight-supply month. There were thirty-three single-family closings, up about 74% from a year earlier, at a $1.5 million median, sale-to-list near 101%, and a 40-day average DOM. With 50 homes for sale, supply fell to about 1.5 months, 40% lower than September 2025. The $2.16 million average sitting far above the median says the month’s mix was heavy at the top. Those facts describe market conditions. They do not price any one house.
William Pitt Tracker and Homix: Same Month, Different Filters
William Pitt Sotheby’s Bedford Market Tracker for September 2026 (single-family unless noted) uses a Bedford-area boundary that is broader than the town line, and it lines up closely with the HL price, volume, and DOM picture:
- Units sold (September, SF): 34 (+70.0% YoY; +78.9% versus September 2024)
- Median sold: about $1.5 million (+25.1% YoY; −21.5% versus September 2024); average: about $2.1 million (+61.7% YoY)
- Average DOM: 40 (−7.9% YoY); percentage of asking: 99% (+3.6% YoY)
- Average $/SF: $486 (+3.2% YoY); new SF listings: 27 (+42.1% YoY)
- YTD SF sold (January–September): 174 (+6.1% versus YTD 2025)
- September other product types: Condo/Co-op 3 (−40.0% YoY), Multi-Family 1
- Total monthly inventory (all product types): 143 units (+40.2% YoY; +78.8% versus September 2024)
Source: William Pitt Sotheby’s Bedford Market Tracker (September 2026). Brokerage dashboard figures are deemed reliable but not guaranteed.
The two brokerage series agree on the headline: thirty-three or thirty-four closings, a $1.5 million median, and a 40-day DOM. They part ways on sale-to-list (HL 101.03% versus WP 99%) and on inventory direction. HL counts 50 single-family homes for sale, up only 4.2% year over year, while WP’s 143-unit figure covers all product types and is up 40.2%. That is not a contradiction to average away. It is the same lesson as in the firm’s Harrison housing market 2026 post: read the filter before quoting the number. Note too that WP shows the September median down 21.5% versus September 2024 even while it is up 25.1% versus 2025. One month’s median in a thirty-sale market is a noisy number.
Homix’s OneKey-based Bedford report (data as of October 8, 2026) is a much smaller cut:
- Single-family, September 2026: median $1,625,000 versus $1,360,000 in September 2025 (+19.5%); 7 closed versus 5; homes for sale 22 versus 21; average DOM 22 versus 42; % of original list 107.4% versus 103.1%; new listings 10 versus 8; about 3.4 months of supply
- Single-family, 12 months through 09/2026: median $1,588,250 versus $1,625,000 (−2.3%); closed 78 versus 77 (+1.3%); average DOM 42 versus 42; % of original list 102.2% versus 103.7%
- Condo: no September sales; one condo sale in the trailing 12 months
Source: Homix Bedford market report. Homix notes its figures are calculated from OneKey MLS data, and small samples can make percent changes look extreme. Its 12-month series is the useful part here. On 78 closings, the trailing-year median is essentially flat (−2.3%) and DOM is unchanged at 42 days, a much calmer picture than the +23.9% September headline.
Why Bedford Headlines Mislead
Every series above shows a Bedford median around $1.5 to $1.6 million, and the September year-over-year jump is easy to misuse. Common failure modes when someone quotes it as “the Bedford market”:
- Mix shift versus price movement: HL’s average ($2,161,708) is about 44% above its median ($1,500,000), and the average rose 61.1% year over year while the median rose 23.9%. A handful of large estate closings can lift both numbers without any change in what a typical in-hamlet house would bring. Homix’s flat 12-month median is the counterweight.
- Monthly versus trailing data: HL’s YTD median is up about 6% over 2025, and Homix’s trailing-12-month median is down 2.3%. A single +24% September is not a 24% appreciation rate, and a time adjustment built on it would overshoot.
- Estate parcels versus in-hamlet homes: Multi-acre parcels with barns, pools, and long private drives, and smaller lots in Bedford Hills or Katonah, are not interchangeable comps. Lot size and utility, private well and septic, and outbuildings need data support, not assumptions.
- Sale-to-list is not a blanket premium: About 101% (HL) or 99% (WP) describes September closed outcomes in aggregate. It does not mean every listing clears at or above asking. With 27 new single-family listings in September (WP, +42.1% year over year), pricing inside the subject’s band matters more than the town average.
- Thin product types: Three condo/co-op sales (WP) and zero condo sales (Homix) are not a basis for any detached single-family conclusion, and vice versa.
For a deeper primer on how appraisers parse medians, months of supply, DOM, and sale-to-list, see Market Conditions and How Appraisers Analyze the Stats.
How Appraisers Read Bedford’s Competitive Sets
Market-conditions commentary in a Bedford appraisal is built from the sales that actually compete with the subject, not from the area headline alone.
- Confirm the location first: Bedford Village, Bedford Hills, Katonah, or Bedford Corners. Pull comps inside that set before expanding to neighboring Pound Ridge, Mount Kisco, North Castle, or Lewisboro sales.
- Bracket lot size and utility: Multi-acre parcels are bracketed against similar acreage, with attention to usable versus encumbered land. In-hamlet lots are bracketed against in-hamlet sales.
- Time adjustments from the matched set: With the September median up about 24% but the trailing-year median roughly flat, a supported time adjustment comes from paired and repeat sales in the subject’s band, not from the monthly headline.
- Inventory as absorption context: About 1.5 months of single-family supply (HL) and 3.4 months on Homix’s narrower cut both sit in seller’s-market territory. Rising new listings mean the appraiser should document active and pending competition inside the subject’s own price and quality band.
- Assessment versus market value: Assessed value is not market value. Tax-grievance work compares the assessment to a current, supportable market-value opinion. See tax grievance.
Private-Use Assignments When the Month and the Year Disagree
When the September median says +24% and the trailing year says roughly flat, AVM estimates and area averages are least reliable, and the effective date carries more weight. For files that must stand up for counsel or a fiduciary:
- Estate / date-of-death: A retrospective opinion for Form 706, probate, or fiduciary accounting uses market evidence knowable as of the date of death. An executor who quotes a September 2026 median for a spring 2026 date of death is mixing effective dates. See estate appraisal, date-of-death appraisal, and date of death vs current market value.
- Divorce / equitable distribution: Current or retrospective (including date-of-commencement) valuations of the marital residence. When the monthly median and the 12-month median point in different directions, the effective date and the matched set, not the headline, decide the number. See divorce appraisal and date-of-commencement appraisals in NY divorce.
- Attorney and fiduciary briefing: Counsel often need a plain-English read of whether a proposed buyout or listing price is consistent with recent matched sales, not with the town median or an AVM alone. Private USPAP reports differ from lender forms. See private vs lender appraisals and the firm’s attorney resources.
What Helps a Bedford Market-Conditions Read
- Confirm Bedford Village vs Bedford Hills vs Katonah vs Bedford Corners, and whether the data filter matches that area
- Pull closed MLS sales that match the subject’s location, GLA band, condition, and lot size and utility
- Record list price, sale price, concessions, and DOM for each competing sale
- Note active and pending inventory inside the subject’s price and quality band, not only the town total
- Document well, septic, outbuildings, and usable acreage for both subject and comps
- Check whether a median move reflects price change or a shift in the mix of sales, using trailing 12-month data
- Reconcile HL single-family “units for sale” with brokerage all-product inventory before quoting months of supply
Final Thoughts
As of the September 2026 Houlihan Lawrence Bedford single-family report, Bedford’s market is tight on the five metrics that matter for appraisal commentary. The report shows a $1,500,000 median on thirty-three closings, sale-to-list near 101%, a 40-day average DOM, and about 1.5 months of inventory, with closings up 73.7% and supply down 40% year over year. The William Pitt tracker backs up the price, volume, and DOM figures. Homix’s narrower cut and its flat 12-month median are a reminder that one strong month is not a trend. Mix-driven medians mislead. Those facts describe market conditions. They do not price any one house.
A defensible Bedford appraisal still starts with physical evidence and matched sales from the right part of town. That set is then placed against the area statistics as context. Whether the purpose is estate settlement, divorce, tax grievance, or a private purchase opinion, Madison & Park builds the analysis that way across Westchester, Manhattan, and Greenwich CT. Dave Lister, SRA, is a New York certified residential appraiser and is Licensed in Connecticut; Court Approved status applies in New York only.
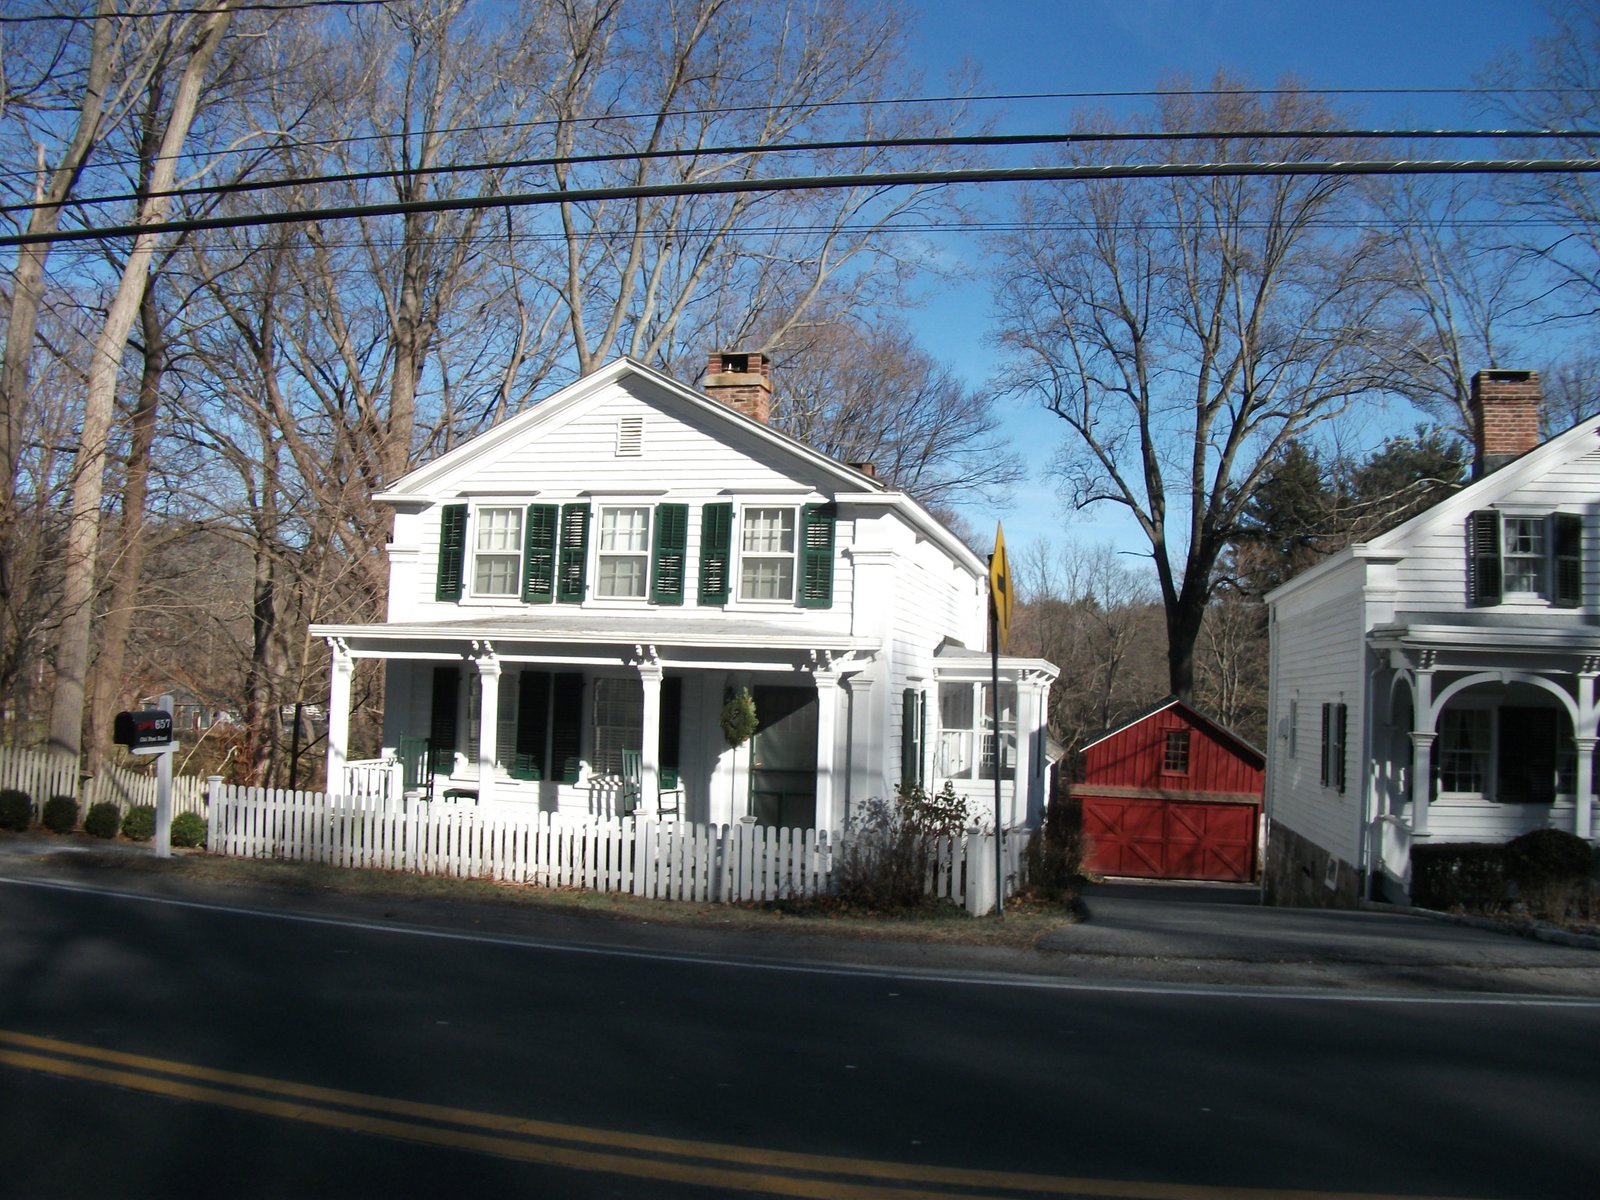
Hero photo: House in the Bedford Village Historic District, Bedford, NY, by Doug Kerr, via Wikimedia Commons, licensed CC BY-SA 2.0; resized.
Need an Appraisal in Bedford?
Whether for estate planning, divorce, tax grievance, or a private market opinion, we provide thorough, professional valuation services across Westchester, Manhattan, and Greenwich CT.
Get a Free Quote